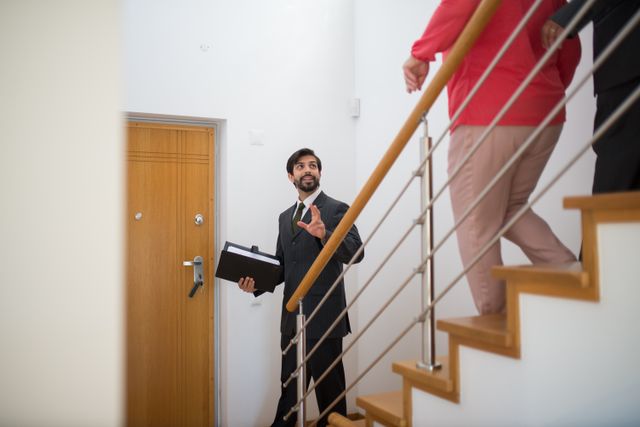
To effectively manage a residential property portfolio or simply keep track of your primary residence, you must first understand what a property appraisal actually represents. Real estate professionals offer appraisals as an estimated guide to what a home might fetch in the current market. This estimate relies heavily on local sales data, current demand, and the agent’s firsthand experience within that specific neighborhood. It is completely distinct from a formal bank valuation, which is a legally binding assessment conducted by a certified valuer for mortgage or tax purposes.
Because an appraisal acts as a dynamic snapshot of local buyer sentiment, its relevance changes alongside the economic climate. Property owners often mistake these market checks as something only required when a sale is imminent. In reality, staying informed about your property’s changing equity is a foundational element of sound financial planning. Recognizing the subtle shifts in your local market landscape helps you make calculated decisions regarding refinancing, renovations, or future investments.
Regular assessments ensure that you are never caught off guard by sudden shifts in the economy. A home is typically an individual’s largest financial asset, yet many owners go years without checking its actual market position. By treating appraisals as a routine health check for your finances, you gain a clearer picture of your overall net worth and open up opportunities that might otherwise remain hidden.
The Ideal Frequency for Routine Market Updates
For the vast expanse of steady property owners, a general rule of thumb is to arrange a property appraisal once every twelve to twenty-four months. Requesting an update annually aligns perfectly with standard personal financial reviews, allowing you to update your household balance sheets with realistic figures. A single year provides enough time for subtle market movements to accumulate into a noticeable shift in value, whether that movement is driven by local infrastructure or broader economic trends.
In highly active real estate markets experiencing rapid capital growth or sudden downturns, shortening this window to every six months can be highly beneficial. When transaction volumes are high and properties are selling well above reserve prices, waiting a full year can leave you with completely outdated expectations. Conversely, during a localized market correction, a biannual check lets you adjust your long-term expectations and protects you from making poorly timed financial commitments based on old data.
Consistently monitoring your property’s position every one to two years also builds a constructive professional relationship with local real estate agents. These specialists track micro-movements across specific streets and school zones daily. Keeping a regular line of communication open ensures you receive hyper-local insights long before they filter through to major national media outlets or generalized quarterly data indexes.
Trigger Events That Warrant an Immediate Appraisal
While standard annual check-ins serve as a fantastic baseline, specific life milestones and property adjustments demand an immediate, out-of-cycle market assessment. The most common trigger is the completion of substantial home renovations. Whether you have added an extra bedroom, completely remodeled an outdated kitchen, or installed an expansive outdoor entertaining area, these structural changes instantly alter your home’s appeal. An immediate appraisal quantifies the exact return on your renovation investment and clarifies whether you have successfully added value.
Major life changes represent another critical catalyst for an immediate market update. Decisions involving marriage, a expanding family, career relocation, or entering retirement invariably impact your long-term housing requirements. If you need to downsize to free up retirement capital or upsize to accommodate a growing household, knowing your exact current selling position dictates your realistic purchasing budget for the next property.
Refinancing an existing mortgage also calls for a proactive appraisal before you officially engage with a lending institution. If your property’s value has increased significantly since you initially signed your loan documentation, your loan-to-value ratio changes in your favor. Armed with a fresh appraisal, you can confidently negotiate lower interest rates with your bank or look into unlocking accumulated equity to purchase an investment property or consolidate other debts.
Why Keeping an Accurate Track of Equity Matters
Accumulated equity is the hidden engine of wealth creation for average homeowners, yet it remains completely invisible without a fresh property appraisal. Equity represents the difference between what your home is currently worth in the open marketplace and the remaining balance on your mortgage. When property values climb steadily over a few years, your equity grows without you having to make extra principal payments on your loan.
Knowing your precise equity position allows you to approach wealth generation proactively rather than reactively. Many successful property investors build their portfolios by utilizing the usable equity in their primary residence as a deposit for an investment apartment or house. Without a current appraisal, you might mistakenly assume you lack the necessary funds to expand your portfolio, missing out on valuable market cycles and compounding long-term growth.
Furthermore, accurate equity tracking plays an essential role in risk mitigation and insurance management. If building costs rise sharply alongside property values, your existing home insurance policy might leave you dangerously underinsured. Comparing a realistic market appraisal against your current policy coverage ensures that your insurance payouts would genuinely cover the cost of rebuilding your asset in the event of an unforeseen disaster.
How to Prepare Your Property to Get the Most Accurate Result
To ensure that your scheduled appraisal yields the most accurate and useful data possible, you should treat the process with a degree of deliberate preparation. While an appraisal is less formal than a bank valuation, presenting your home in its absolute best light encourages the agent to look at top-tier comparable sales in the area. Simple tasks like clearing clutter, maximizing natural light, and ensuring basic garden maintenance is completed can positively influence the final figure.
Provide the appraising agent with a detailed list of all hidden improvements made to the property during your ownership. Features like upgraded insulation, solar panel systems, modern ducted air conditioning, or structural rewiring are easily missed during a standard walkthrough but add genuine appeal for modern buyers. Documenting these hidden upgrades helps the agent justify a higher pricing tier when comparing your home to recently sold properties nearby.
Ultimately, staying informed through regular property appraisals empowers you as a homeowner. Whether you choose a strict twelve-month schedule or tie your updates to major property renovations, having an accurate grip on your property’s true value removes the guesswork from your long-term financial journey. It ensures you are always ready to act swiftly when the right financial or lifestyle opportunity presents itself.